Defaulting on a car loan can result in repossession, credit damage, and additional debt if the vehicle’s sale does not cover the remaining loan balance. The steps a lender can take depend on your loan terms, payment history, and state laws. This guide explains how car loan defaults lead to repossession and what options you may have to handle the situation. If you are facing a possible repossession, a bankruptcy attorney can help you understand the legal solutions available for your circumstances.
Some lenders can repossess your vehicle after only one missed monthly payment, depending on state laws and the terms of your loan agreement. Once repossessed, lenders typically auction it to recover costs; if this sale doesn’t cover your entire loan balance, then any deficiency balance could still exist and require payment to be covered. If you have difficulty meeting your loan payments, contact your lender immediately.
Most will work with you to restructure the repayment plan or reduce late fees and interest charges as quickly as possible. The Pope Firm may help you strategize how best to address multiple debts. Debt settlement solutions could allow you to reallocate budget items and catch up on payments to prevent default on car loans or credit lines. Whether you live in Johnson City, TN, or elsewhere, we have you covered!
Lenders may legally repossess your car if you fail to make payments, a process known as repossession. Auto loans are secured debts using vehicles as collateral; your lender will sell the car at auction to recover their loan balance, but be wary: there could be an outstanding deficiency balance, which means paying any difference between what the car sold for and what you still owe on your loan balance.
It can be challenging to rebuild once your credit has taken a hit after repossession. Furthermore, it could make loans and credit more difficult, especially if you need to finance another vehicle. Repossessions typically remain on your report for seven years, although the effect should lessen over time.
Most lenders are flexible in helping borrowers avoid default. If you know you will miss a loan payment, contact your lender as soon as possible to explain your circumstances, and they may offer solutions like:
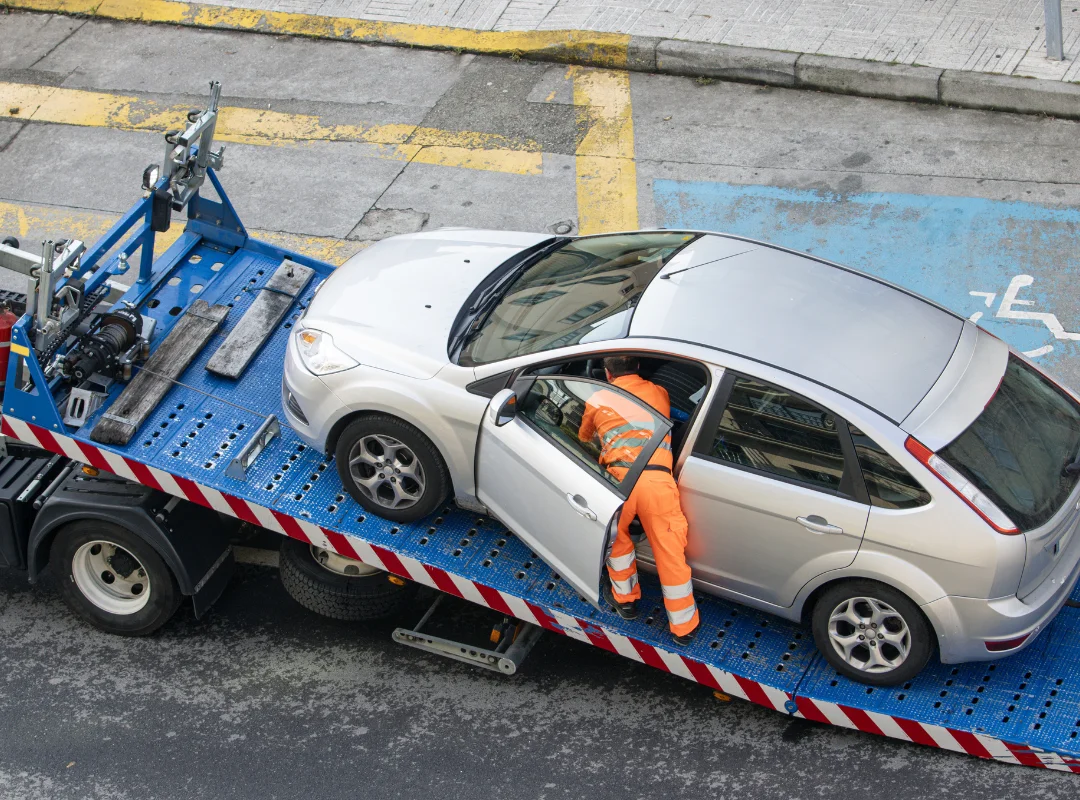
Repossession may not always be avoidable once lenders initiate repossession proceedings, but there are ways to lessen its effect. According to the Federal Reserve Bank, paying all past-due amounts and late fees on time can quickly remove your loan from default and prevent further delinquency.
A Deal Lender may be willing to work out a short-term solution if you provide information on your current financial status and demonstrate your ability to pay your loan on an affordable schedule. Filing for bankruptcy should also be a serious consideration, with both Chapter 7 and 13 bankruptcy offering protection from repossession.
Before taking this step, however, professional advice must be sought from a bankruptcy attorney who can help clarify your options more clearly while helping negotiate with lenders and recommend loan modification or debt settlement as other possible solutions.
If you’re facing the threat of car repossession or struggling with loan defaults, don’t wait until it’s too late. Our team of experienced professionals is here to guide you through your options and help you protect your financial future.
The Pope Firm is here to help you regain control of your financial future. We offer comprehensive bankruptcy solutions tailored to your needs, including Chapter 7, Chapter 11, and Chapter 13 bankruptcy services. Whether you’re looking to declare bankruptcy in Tennessee or determine if you qualify, our team will guide you every step of the way. Contact us now!
Got Questions?